What Makes an NRI Account the Best Choice for Managing Overseas Income?
Before deciding which option is the best NRI account in India, consider your income source, currency needs and financial requirements.
For NRIs earning abroad, choosing an Indian bank account involves more than comparing interest rates. The source of income, repatriation needs, flexible account managementall matter. The right account should support overseas income, fund transfers, repatriation and convenient remote banking. Before deciding which option is the best NRI account in India, consider your income source, currency needs and financial requirements.
What should an NRI account help you do?
An NRI account should support the way you manage overseas earnings. Depending on your requirements, important functions include:
- Receiving eligible overseas income
- Holding and managing funds in India
- Making payments and transfers
- Accessing money while living abroad
- Repatriating eligible funds
- Managing the account through digital banking
The right choice therefore depends on the purpose of the account rather than its name alone.
Which account suits overseas income?
An NRE Account is generally suited to eligible overseas earnings brought to India. Both principal and eligible interest are generally freely repatriable, subject to applicable regulations.
An NRO Account is generally used for income earned in India, such as rent, pension and dividends. NRIs receiving both overseas and Indian income may maintain both accounts to keep their finances organised.
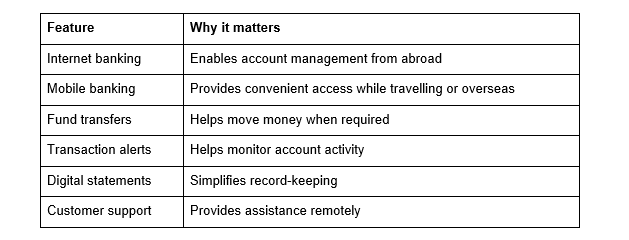
What makes an account convenient from abroad?
Managing finances from another country makes digital access particularly important. Look for:
How important is repatriation?
Repatriation refers to transferring eligible funds from India to an overseas account. For NRIs managing overseas earnings, the ability to move money back when required can be an important consideration when choosing an account.
NRE funds are generally freely repatriable, while NRO funds are subject to prescribed limits, taxes and documentation. Therefore, consider not only whether funds can be transferred abroad, but also the conditions and documentation involved.
What about interest and taxation?
Consider interest earnings alongside liquidity and tax treatment. Interest on an NRE Account is generally exempt from Indian income tax while the account holder continues to qualify as an NRI under applicable rules.
The NRO Savings Account is subject to taxation under Indian laws. The interest earned on your IDFC FIRST Bank NRO account is taxed at 30% plus applicable surcharge and cess. This is known as Tax Deducted at Source (TDS). However, you may seek relief under the Double Taxation Avoidance Agreement (DTAA) if your country of residence has such an agreement with India.
How can you identify the best option?
Before you open an NRE account online, consider:
- Is the money coming from overseas or Indian income?
- Do you need the funds to remain freely repatriable?
- Will you regularly transfer money between countries?
- How important are mobile and internet banking facilities?
- What charges and account conditions apply?
- Do you need an NRE Account, NRO Account or both?
- Are the account’s tax and repatriation rules suitable for you?
Comparing these factors gives you a more useful basis for identifying the best NRI account in India for your needs.
Eligible NRIs may be able to open an NRE account online, subject to the bank’s documentation and verification requirements. With an IDFC FIRST Bank NRE Savings Account, customers can benefit from monthly interest credits, full repatriability of principal and interest, tax-exempt interest subject to applicable regulations, and convenient access through mobile and net banking.
Conclusion
The best NRI account in India is not necessarily the one offering the most attractive headline feature. For overseas income, an NRE Account can provide a useful combination of rupee-based banking, tax-efficient savings and easy repatriation. Before you open an NRE account online, compare the account’s purpose, tax treatment, repatriation rules, digital banking facilities, services and costs to ensure it aligns with your financial requirements.
FAQs
Which account is generally used for overseas income?
An NRE Account is generally designed for eligible overseas earnings brought to India.
Can an NRI maintain both NRE and NRO Accounts?
Yes. Maintaining both can be useful when an NRI receives overseas earnings and income generated in India.
Is NRE Account interest taxable in India?
It is generally exempt from Indian income tax while the account holder qualifies as an NRI under applicable rules.
Can I open an NRE Account online?
Many banks provide online application facilities for eligible NRIs, subject to KYC and verification requirements.
What should I compare before choosing an NRI Account?
Compare purpose, repatriation, taxation, digital facilities, charges, documentation and customer support.